Showing posts with label Mutual funds. Show all posts

Saturday, November 5, 2016

Quoted in India Today

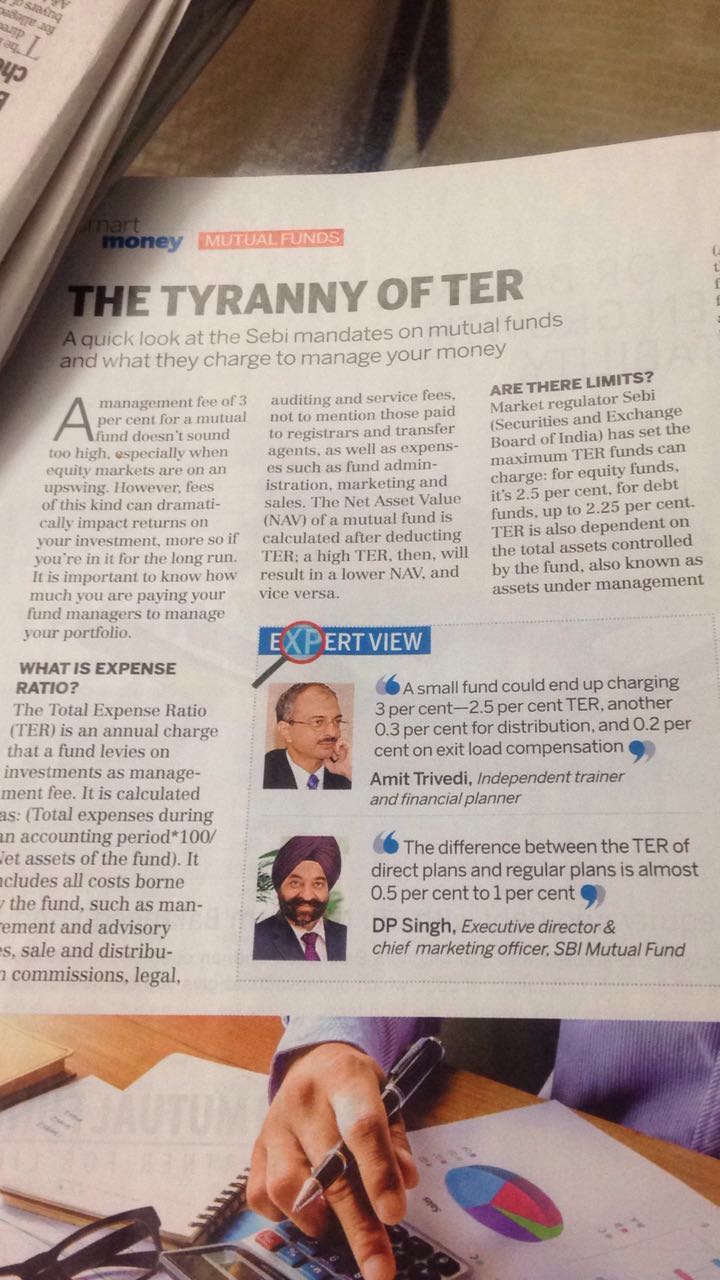
In a story related to the TER on mutual funds, my quote was taken by India Today.

Here is the photo of the relevant page


Monday, October 24, 2016

A good investment option amidst volatility

We looked at various asset allocation schemes last time. This time, we will discuss a variation of these schemes - dynamic asset allocation schemes.

Click on the link here to read further.

____________________________________________________________________________________

The English translation is as under:


Last time, we covered asset allocation funds. This time we will look at a variant of the same, known as “dynamic asset allocation” funds. While we discussed about investing in multiple asset categories, the focus of the discussion was about maintaining certain proportion in each of the two or three asset categories.
However, periodically, when one asset category becomes costly, does it make sense to reduce the allocation? Similarly, should one increase the allocation in the asset that has become cheaper? There is a school of thought that suggests, “Yes, we should”.
Mutual fund companies have come up with schemes that work on such principles. These schemes invest in more than one asset categories – in most cases these invest in two assets. Most such schemes allocate money between equity and debt.
The allocation between equity and debt is altered periodically. In order to determine the allocation to the two asset categories, there are two approaches:
1.     The fund manager alters the allocation based on his/her views on the two asset categories.
2.     The allocation would change on the basis of some pre-decided formula.
In the first case, when the fund manager is bearish on equity market, the scheme would reduce equity exposure. However, when one is bullish about equity, the allocation would go up.
In the latter, most often, valuation determines how much should be allocated where. The allocation would be reduced from (or increased in) the asset that has become costly (cheaper) as indicated by certain valuation parameters. However, some of the schemes only look at valuation of equity. There is at least one scheme that compares the valuation of equity and debt and changes the allocation accordingly.
The valuation parameters:
For the purpose of evaluating equity valuation, most consider the P/E ratio or the P/BV ratio. Both these ratios are popular indicators of valuation. As a thumb rule, it is believed that higher the number, costlier the market (or a sector or a stock). Fund schemes follow a certain pre-defined pattern through which the allocation in equity is reduced step-by-step when the valuation goes up and increased when the valuation goes down.
In one case, the scheme’s allocation is altered based on the gap between the yield on Government Security with 10-year maturity and the “earnings yield” for equity. The earnings yield is the inverse of P/E ratio.
These are schemes designed to reduce short-term fluctuations in the scheme’s NAV. At the same time, such schemes are expected to deliver at least as much as a fund that evenly allocated money between equity and debt.
Very often, investors have compared such schemes to pure equity funds. That is a mistake. Given that these schemes invest at least some proportion and often a large chunk in debt securities, it would be improper to compare these with pure equity funds.
Should an investor consider investing in such schemes? Well, that entirely depends on whether the investor needs such a scheme in the first place. Having said that, one may consider such a scheme with an expectation of reduced price fluctuations compared to a hybrid scheme that does not change the allocation.
It’s a good category to explore for investors. However, a deeper analysis is warranted since the alternatives can have significant differences among them.
-        Amit Trivedi
The author runs Karmayog Knowledge Academy. Recently, Amit has authored a book titled “Riding the Roller Coaster – Lessons from Financial Market Cycles We Repeatedly Forget”. The views expressed are his personal opinions.

Monday, October 3, 2016

Asset Allocation schemes - managed risk, enhanced returns


Some mutual fund houses have launched schemes known as the “asset allocation schemes”. What are these schemes? How do they operate? Should one consider investing in such schemes? 
Read my article in Mid-day Gujarati edition today on the subject of asset allocation ...

_________________________________________________________________________________

The English translation of the same is as under:

Some mutual fund houses have launched schemes known as the “asset allocation schemes”. What are these schemes? How do they operate? Should one consider investing in such schemes?
Before answering the above questions, it is important to understand what asset allocation means. It is a process to allocate one’s investments across various asset categories. The reasons behind asset allocation, the reasons why and how much money is allocated to different asset categories could be either unique to the investor or sometimes based on the fund manager’s view on the opportunities in different asset categories.
Since mutual fund companies cannot customize the schemes for individual investors, the logic of investing the fund’s investments across asset categories cannot be done in line with the investors’ needs. Hence, the objective of the asset allocation schemes launched by mutual fund companies would be to generate better risk-adjusted returns. Some people call these schemes offer peace of mind to investors, as the returns are decent, but the price fluctuations are moderate.
For this purpose, money in the scheme is invested across more than one asset classes. Since the market prices of different assets move differently, the scheme’s NAV exhibits moderate movement only.
Let us assume that a scheme has invested in both equity and debt. As we all understand, market prices of equity and debt do not move together. At some time, when the equity prices could be down, debt might have gone up. This is when the down movement of equity would be compensated partly by the up movement of debt prices.
The reverse may also happen when the debt prices do not move much or move in negative direction, equity might be up.
Thus, the opposite movements tend to cancel each other out partly, which lowers the fluctuation in the NAV of the scheme.
The asset allocation schemes may allocate money across more asset categories. in the Indian mutual fund industry, we have schemes that invest in various combinations of equity, debt and gold.
In certain cases, the schemes define the allocation across the asset categories and keep the same fixed. So, a scheme may invest 60% in equity and 40% in debt. At a pre-defined frequency the allocation would be checked and if required, would be restored to the 60-40 ratio.
Some schemes may give some flexibility to the fund manager to alter the allocation marginally, based on his or her market view. Such schemes depend on the portfolio manager’s abilities to improve the scheme’s performance.
There are some schemes that allow changes to the set percentage allocation based on certain valuation parameters. We will talk about such schemes in our next article.
Till then, keep an eye on the asset allocation schemes. In fact, two categories of funds that we have already covered earlier are Balanced Funds and MIP (or Monthly Income Plans). These are also known as hybrid schemes.
One must be careful to check whether the allocation between equity and debt is fixed at a certain ratio or the fund manager has a leeway to change it as per the outlook. For this purpose, one needs to check the following:
1.     The Scheme Information Document (popularly known as the SID) contains the details of asset allocation allowed. Read the table as well as the text below it., and
2.     The fact sheet contains the details of actual investments made by the scheme. Even when the fund manager has the flexibility to change the asset allocation, more often, the same is not used and the allocation is kept fixed.
If the allocation is kept at a near-constant ratio, one is not so much dependent on the fund manager’s outlook on the different asset categories. However, when the fund manager keeps changing the allocation between equity and debt, it requires skills. These skills can add to the returns, but at the same time are subject to the risk of the fund manager’s judgment being wrong.
Happy investing to you all.
-        Amit Trivedi
The author runs Karmayog Knowledge Academy. Recently, Amit has authored a book titled “Riding the Roller Coaster – Lessons from Financial Market Cycles We Repeatedly Forget”. The views expressed are his personal opinions.


Monday, September 19, 2016

Transcript of today's chat on www.moneycontrol.com

Click on the link below to read through the transcript of today's chat on www.moneycontrol.com

Equity investments simplified


How is the NAV of a mutual fund scheme calculated? Do the inflows and outflows in the scheme impact the NAV?

The other day, in an investment seminar someone asked a question: “How is the NAV calculated?” He also wanted to know if the daily inflows and outflows in the fund by investors impact the NAV calculations apart from the movement in the prices of securities held by the fund.

Read my article in Mid-day Gujarati edition today to understand the NAV calculation:

Mutual Fund NAV calculation


The other day, in an investment seminar someone asked a question: “How is the NAV calculated?” He also wanted to know if the daily inflows and outflows in the fund by investors impact the NAV calculations apart from the movement in the prices of securities held by the fund.
Let us look at both parts of the question and answer each. First of all, what exactly is NAV in the context of a mutual fund?
NAV is the Net Asset Value of the fund – popularly mentioned as NAV per unit. In the accounting parlance, NAV is the other name for book value. This is the value of the scheme’s total assets less the liabilities. If you simply add up all the assets and deduct all the liabilities of the fund, you get the value of the net assets. Divide this by the number of outstanding units and you get the NAV per unit.
NAV per unit = (total assets of the scheme – total liabilities of the scheme)
---------------------------------------------------------------------------
                    Number of outstanding units
This looks simple. Having reached till here, we need to understand what the fund’s assets and liabilities are.
A mutual fund scheme invests in many securities as per the investment objective. We have discussed this earlier. The market value of these securities (or investments) forms the major part of the fund’s assets. Apart from that there are some minor contributors, e.g. interest accrued but not received, dividend declared but not received yet, proceeds receivable on sale of investments, money parked in money market instruments and bank balance. All these are examples of the fund’s assets. The value of investments has to be taken as the current market price, which is an indicator of the realizable value of the scheme’s assets.
Now come the liabilities. We saw earlier that a mutual fund cannot borrow money for the purpose of investing. The only exception allowed is when the fund has to meet redemptions or dividend payouts and is unable to liquidate the investments due to some critical factors like a market meltdown or illiquidity in the system. Such a liability, if exists, should be added to the fund’s total liabilities. At the same time, there are some liabilities that exist on a regular basis. These are fees payable to various constituents like the asset management company, the custodian, bankers, R & T agent, directors, auditors, distributors, etc. there could also be liability on account of payment to be made for securities purchased. All the liabilities get added up and these have to be deducted from the fund’s assets.
As mentioned earlier, this would give the net assets of the fund.
Dividing this by the number of outstanding units would give the NAV per unit. This NAV has to be calculated on a daily basis. The accounts students among the readers can easily make out that in order to arrive at the fund’s net assets, the scheme’s balance sheet must be prepared. Since the NAV is calculated on a daily basis, the balance sheet is also prepared daily. Which business would be preparing final balance sheet daily? This is another example of the transparency of a mutual fund.
This answers the first part of the question – regarding the calculation of NAV.
Now let us consider the second part of the question. “Do the daily inflows and outflows impact the NAV of a scheme?” as you can see in the answer to the first question; the inflows and outflows into or out of the scheme do not feature in the NAV calculation. However, many keep asking if these inflows and outflows have any impact on the scheme’s NAV.
Well, the short answer is “no, they do not impact the NAV on a daily basis.” However, this is a simplistic answer and only looks at the theory. It is also important to check whether these have any impact on the NAV, at all.
When an investor purchases the units of the scheme, there is an inflow of money in the scheme. The scheme allots units at the prevailing NAV. This is the NAV that has been calculated as discussed earlier. The investor, who submits the purchase application before the cut-off time, gets units at the NAV calculated based on the closing prices for the day. Exactly same process is followed when an investor takes money out of a scheme.
As can be seen, the inflows and outflows do not impact the NAV.
However, when a scheme receives huge inflows in relation to its corpus, the fund manager may not be able to invest all the money immediately. This means, cash would be held in the portfolio for a considerable amount of time. This impacts the future NAV changes since cash and securities may not move together.
This is a small point that must be kept in mind. At the same time, since short term price movement is unpredictable and there is an (almost) equal probability that the prices may move up or down in the short run, this impact may get cancelled out over the years.
-        Amit Trivedi
The author runs Karmayog Knowledge Academy. Recently, Amit has authored a book titled “Riding the Roller Coaster – Lessons from Financial Market Cycles We Repeatedly Forget”. The views expressed are his personal opinions.


Monday, August 22, 2016

You enjoy your holidays and your money works for you, is it possible?


You enjoy your holidays and your money works for you, is it possible?

Read my article on the subject in Mid-day Gujarati edition today.

________________________________________________________________________________
English translation is as under:


How does it sound when your money works for you even when you are enjoying your holidays?
August is the month of festivals and long weekends. Many of us go for mini-vacations – either on some excursions or to meet our families. During such periods, often the money lies idle in the bank accounts. There are no options where the money can be parked to earn some returns.
Bank fixed deposits are available for a minimum period of 15 days if the amount is small. That means, the money remains idle in savings or current accounts. With most banks, the current accounts do not earn a single rupee and the interest on savings accounts is a low 4% p.a.
In such cases, mutual funds offer an incredible opportunity in form of liquid funds. It is possible to invest amounts as small as Rs. 10,000 and even for weekends. Many large companies use this facility offered by mutual funds to park money for weekends. The liquid funds are open-ended mutual funds and hence the transaction can be done on any business day. Let us say, there is a holiday on a particular Monday, making it a long 3-day weekend – Saturday, Sunday and Monday.
If you have surplus money in your bank account on Friday before these holidays, you can invest the same in a liquid fund and simultaneously file for redemption such that you get the money in your bank back on Monday. In case you do not need the money on Monday, you may continue to stay invested.
Mutual funds offer a great flexibility in terms of not declaring the investment period in advance. You may invest your money in a liquid fund without mentioning the date of redemption in advance. You may stay invested till the time you do not need the money.
As per the website of Value Research, a leading portal for mutual fund information, the liquid funds have delivered the following returns in the past:
Table 1:
Period
Returns (p.a.)
Last week
6.76%
Last month
7.08%
Last 3 months
7.36%
Last year
7.83%
(Disclaimer: Past performance may or may not be sustained in future)
As you can see, the rates of return are around 7% p.a. However, you may also observe that the returns for the shorter periods are lower than the longer periods. This is not like a bank fixed deposits where they offer lower interest rates for shorter periods and higher for longer periods.
This has happened in case of liquid funds since in the last some time, the interest rates have come down. Liquid fund is a product that responds to the changes in interest rates in the market very fast. If the interest rates in the economy start going down, the liquid fund returns would get adjusted and if the rates start going up, the liquid fund returns would improve.
Let us do some Math with the above numbers. If you have a surplus of Rs. 5 lacs to be invested for a long weekend (3 days), how much do you earn?
Table 2:
Assumed rate of return
Money earned
6.76%
Rs. 277.81
7.08%
Rs. 290.96
7.36%
Rs. 302.47
7.83%
Rs. 321.78
(The rates of return are taken from table 1)
If you do not need money, as we mentioned earlier and you keep the money in a liquid fund for 10 days, the earnings would be as under:
Table 3:
Assumed rate of return
Money earned
6.76%
Rs. 926.03
7.08%
Rs. 969.86
7.36%
Rs. 1,008.22
7.83%
Rs. 1,072.60
(The rates of return are taken from table 1)
If in a year, you get four to five such opportunities, we are now talking about serious money.
Liquid funds also offer facilities to transact through SMS, increasing the convenience. In fact, just before writing this article, I invested some money in a liquid fund just by sending an SMS. The redemption from the fund account also happens through an SMS. All you need to do is to get a one time mandate registered.
So, what are you waiting for? Enjoy your holidays and let your money work for you. The earning would take care of part of the expenses.
-        Amit Trivedi
The author runs Karmayog Knowledge Academy. Recently, Amit has authored a book titled “Riding the Roller Coaster – Lessons from Financial Market Cycles We Repeatedly Forget”. The views expressed are his personal opinions.